FinanceLow
Paraguay’s President Resigns Over a Bank Collapse: What Happened and Why Should Readers Care?
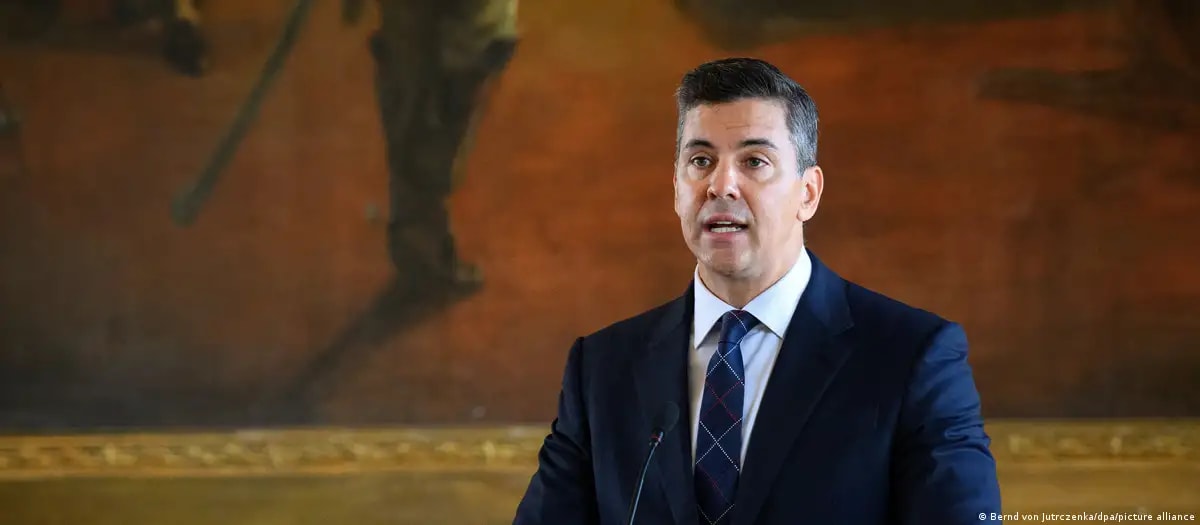
Paraguayan President Santiago Peña resigned after central bank authorities seized Ueno Bank, locking 3 million accounts and triggering massive financial turmoil.
By Betini Udom Published 5 min read Editorial Policy Report a correction
What caused the president of Paraguay to resign so suddenly?
On 5 November 2026, Paraguayan President Santiago Peña announced his resignation in a televised national address. The immediate trigger was not a political disagreement or election defeat, but the sudden financial collapse of Ueno Bank—a prominent digital commercial lender in Paraguay. Two days prior, on 3 November 2026, the Central Bank of Paraguay seized control of Ueno Bank after determining that its capital reserves had fallen to dangerous levels. The regulatory intervention immediately locked the accounts of nearly 3 million depositors, blocking individuals, small businesses, and state pension funds from accessing their cash.
The account freeze triggered widespread public outrage and street protests in the capital city of Asunción. As demonstrators demanded accountability, members of the Paraguayan Congress initiated emergency impeachment proceedings against Peña, citing his close political and historical business ties to the bank's leadership. Facing near-certain removal by lawmakers and escalating civil unrest, Peña chose to step down to preserve institutional stability, handing executive authority to Vice President Pedro Alliana.
What was Ueno Bank, and how did it grow so quickly?
Ueno Bank began as a small financial institution before transforming into a high-tech digital lender. Over a short period, it aggressively expanded its market share by offering digital account opening, low-friction mobile payments, and high-yield savings products. By late 2026, the institution had gathered roughly 2.9 million to 3 million account holders—representing nearly half of Paraguay's total population.
However, this rapid expansion occurred alongside significant regulatory concessions. Under Peña's administration—who previously served as the country's finance minister before becoming president in 2023—the bank was authorized to handle substantial public sector accounts, state payroll deposits, and national pension holdings. This rapid influx of public money gave the bank the appearance of absolute stability, even as its internal risk management failed to keep pace with its rapid asset growth.
Why did the central bank step in, and what is a solvency ratio?
Central banks act as the primary financial referee in any nation. Their main job is to ensure that commercial banks hold enough high-quality liquid assets (cash and easily sellable bonds) to honor customer withdrawals at any time. The key metric used to measure this health is called the solvency ratio.
A solvency ratio compares a bank’s available capital against its total credit exposure and risk-weighted assets. Think of it as a safety margin: for every ₦100 or $100 a bank lends out or invests, regulations require it to maintain a fixed minimum buffer of its own money to absorb potential loan defaults. According to official disclosures from the Central Bank of Paraguay, Ueno Bank's solvency ratio plummeted below 50% of the legally required minimum threshold. In plain terms, the bank had burned through its capital cushion, leaving it unable to guarantee that it could cover customer deposits. When a bank's capital drops this severely, central banks step in immediately to freeze operations, prevent a full-scale panic, and initiate resolution procedures.
How do account freezes and deposit insurance work when a bank fails?
When financial regulators take control of a distressed bank, they temporarily freeze all outgoing transactions, ATM access, and online transfers. This pause prevents a "bank run"—a chaotic scenario where millions of customers simultaneously attempt to withdraw their funds, which would instantly drain whatever liquid cash the bank has left.
Once accounts are frozen, the official resolution process relies on a Deposit Guarantee Fund (or deposit insurance scheme). How this mechanism works step by step:
- Asset Assessment: Regulatory auditors evaluate the bank’s remaining assets, loans, and cash reserves to determine total losses.
- Insured Payouts: Deposit insurance guarantees everyday account holders up to a statutory limit (a capped amount per depositor). Small savers are typically reimbursed first directly from the national deposit insurance reserve.
- Uninsured & Pension Funds: Account balances exceeding the insurance cap—such as major corporate accounts or large institutional pension funds—must wait until the liquidator sells off the failed bank's assets (loans, buildings, and technology) to recover pennies on the dollar.
In Paraguay’s case, because institutional state funds and millions of everyday pensioners were locked out simultaneously, the immediate liquidity shock severely disrupted daily commerce across the economy.
What does this story tell us—and what remains unknown?
This crisis underscores a vital rule of personal finance and national governance: **rapid digital expansion cannot replace sound banking supervision.** When commercial banks grow rapidly by offering unsustainably high yields or taking on massive public sector deposits without strict capital buffers, the system becomes vulnerable to systemic shocks.
What the official reports confirm:
- The central bank's intervention was triggered directly by a severe capital deficit.
- Vice President Pedro Alliana is slated to lead the country under constitutional succession rules.
- The central bank has initiated steps to activate the national deposit protection mechanism to restore access to small account holders.
What remains unknown at this stage (labelled as RainingMoney's reading based on current public filings):
- The precise percentage of missing funds that will ultimately be recovered by institutional depositors and state pension reserves.
- Whether criminal charges will be formally brought against former executive officials once congressional parliamentary immunity decisions are finalized.
What can everyday bank customers learn from a crisis like this?
While this event took place in South America, the mechanics of banking failures are identical everywhere. For everyday readers managing their savings, three key lessons apply:
- Know your deposit insurance limits: Always check the legal deposit protection limit set by your country's regulatory body (such as the NDIC in Nigeria or FDIC internationally). Splitting large savings across multiple licensed institutions ensures all your cash stays within protected limits.
- Be wary of unnaturally rapid growth: When a young financial platform offers interest rates significantly higher than traditional commercial banks, it often indicates the firm is taking higher risks to attract quick capital.
- Institutional ties are not a guarantee: Just because a bank handles government accounts or enjoys political backing does not mean it is immune to capital shortfalls. Regulatory compliance and strong capital ratios are the only true protection for your money.
Sources & Verification
- Sources: Official Regulatory Notices & Parliamentary Filing Statements (5 November 2026)
- Editorial note: This explainer is an original adaptation of the report, RainingMoney has added explanatory context.
Founder and Editor-in-ChiefAbuja
Betini Udom
Founder and Editor-in-Chief of RainingMoney. Covers Nigerian, pan-African and global markets, finance and economic policy.
Author profile & archive →The Money Print
Market intelligence before the market opens.
Pan-African capital flows and the stories behind the numbers, on weekday mornings.